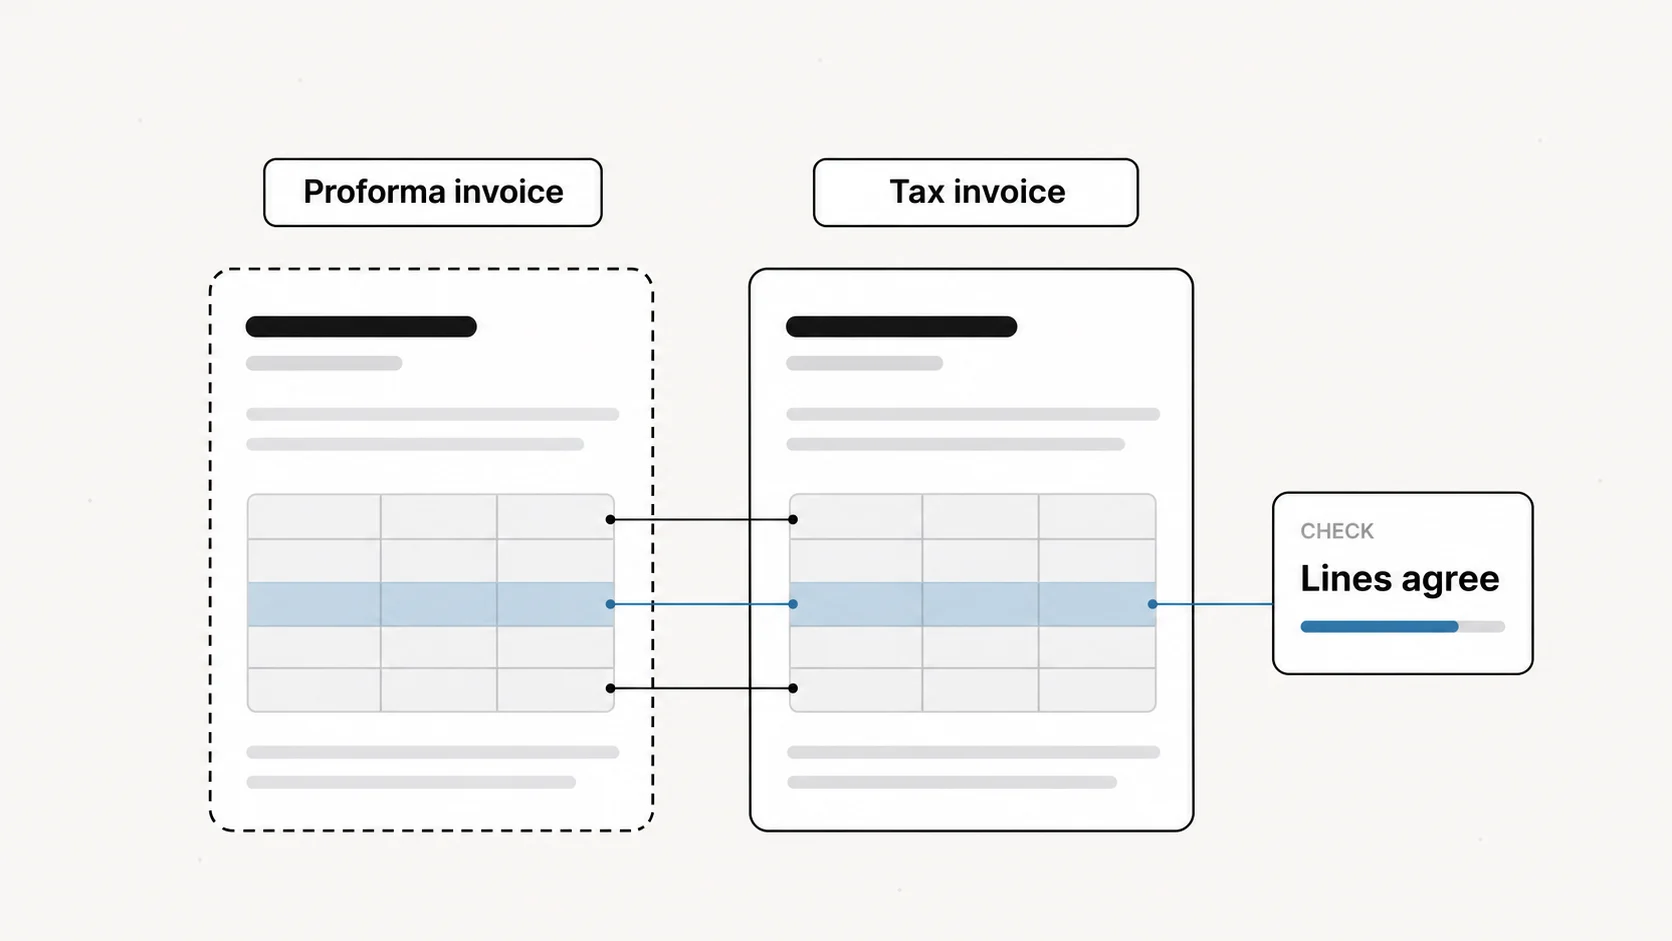
A proforma invoice is a preliminary bill that a supplier sends before the goods are delivered or the sale is confirmed. It lists what will be supplied, the price and the terms, so the buyer can approve the purchase, raise an order or arrange payment. It is not a tax invoice, and it is not recorded as an amount owed.
The US International Trade Administration describes it as "a quote in an invoice format". That is a useful test: the layout looks like an invoice, while the job it does is closer to a quotation.
This guide covers the format, the difference from a tax invoice and a purchase order, and the checks that matter when the final invoice arrives. Document Automation can run those comparisons on the files themselves.
What is a proforma invoice?
A proforma invoice is a commercial document issued before a supply takes place. HMRC's guidance for VAT officers defines pro-forma invoices as "commercial documents that contain some or all of the information normally contained on an invoice, but which do not fulfil that primary function". HMRC VATREC9010.
The spelling varies. Proforma, pro forma and pro-forma all name the same document.
Two things follow from the definition. The supplier has not yet recorded a sale, and the buyer has not yet received a bill to enter as a payable. The same HMRC page says that a pro-forma, in normal circumstances, "cannot be considered to be an accounting document".
What is a proforma invoice used for?
A buyer asks for a proforma when it needs the supplier's terms in writing before committing. The common uses are:
| Use | What the buyer does with it |
|---|---|
| Approval before ordering | Reviews the items, prices and terms, then raises a purchase order |
| Advance payment | Pays a deposit or the full amount before the supplier ships |
| Import arrangements | Applies for an import licence, opens a letter of credit or arranges a currency transfer |
| Internal sign-off | Attaches it to a purchase request so the approver sees the supplier's terms |
The import row comes from the International Trade Administration, which notes that a pro forma "may be required by the buyer to apply for an import license, contract for pre-shipment inspection, open a letter of credit or arrange for transfer of hard currency". It adds that a pro forma may not be a required shipping document. Trade.gov: pro forma invoice.
Proforma invoice format: the fields it carries
There is no single mandatory layout. The International Trade Administration lists the points a pro forma should include. The table follows that list and adds a reference number and an issue date, which a buyer needs in order to compare the offer with the order and the bill.
| Field | Why it matters later |
|---|---|
| Supplier name and address | Identifies who should issue the final invoice |
| Buyer name and address | Keeps the offer attached to the right legal entity |
| Proforma number and issue date | Lets the order and the invoice refer back to one version |
| Buyer's reference | Links the offer to the buyer's request |
| Items, quantities, unit prices and line totals | The baseline for every later comparison |
| Weights and dimensions | Needed for freight and import arrangements |
| Discounts | Explains a difference between list price and billed price |
| Terms of sale and delivery point | States where responsibility for the goods passes |
| Payment terms | States any advance and when the balance falls due |
| Estimated shipping date | Sets the expected timing |
| Validity date | Prices agreed after this date need confirming again |
The label matters as much as the fields. HMRC says pro-forma invoices "should always be clearly described as such and should preferably be endorsed 'This is not a VAT invoice'".
Read the sample proforma
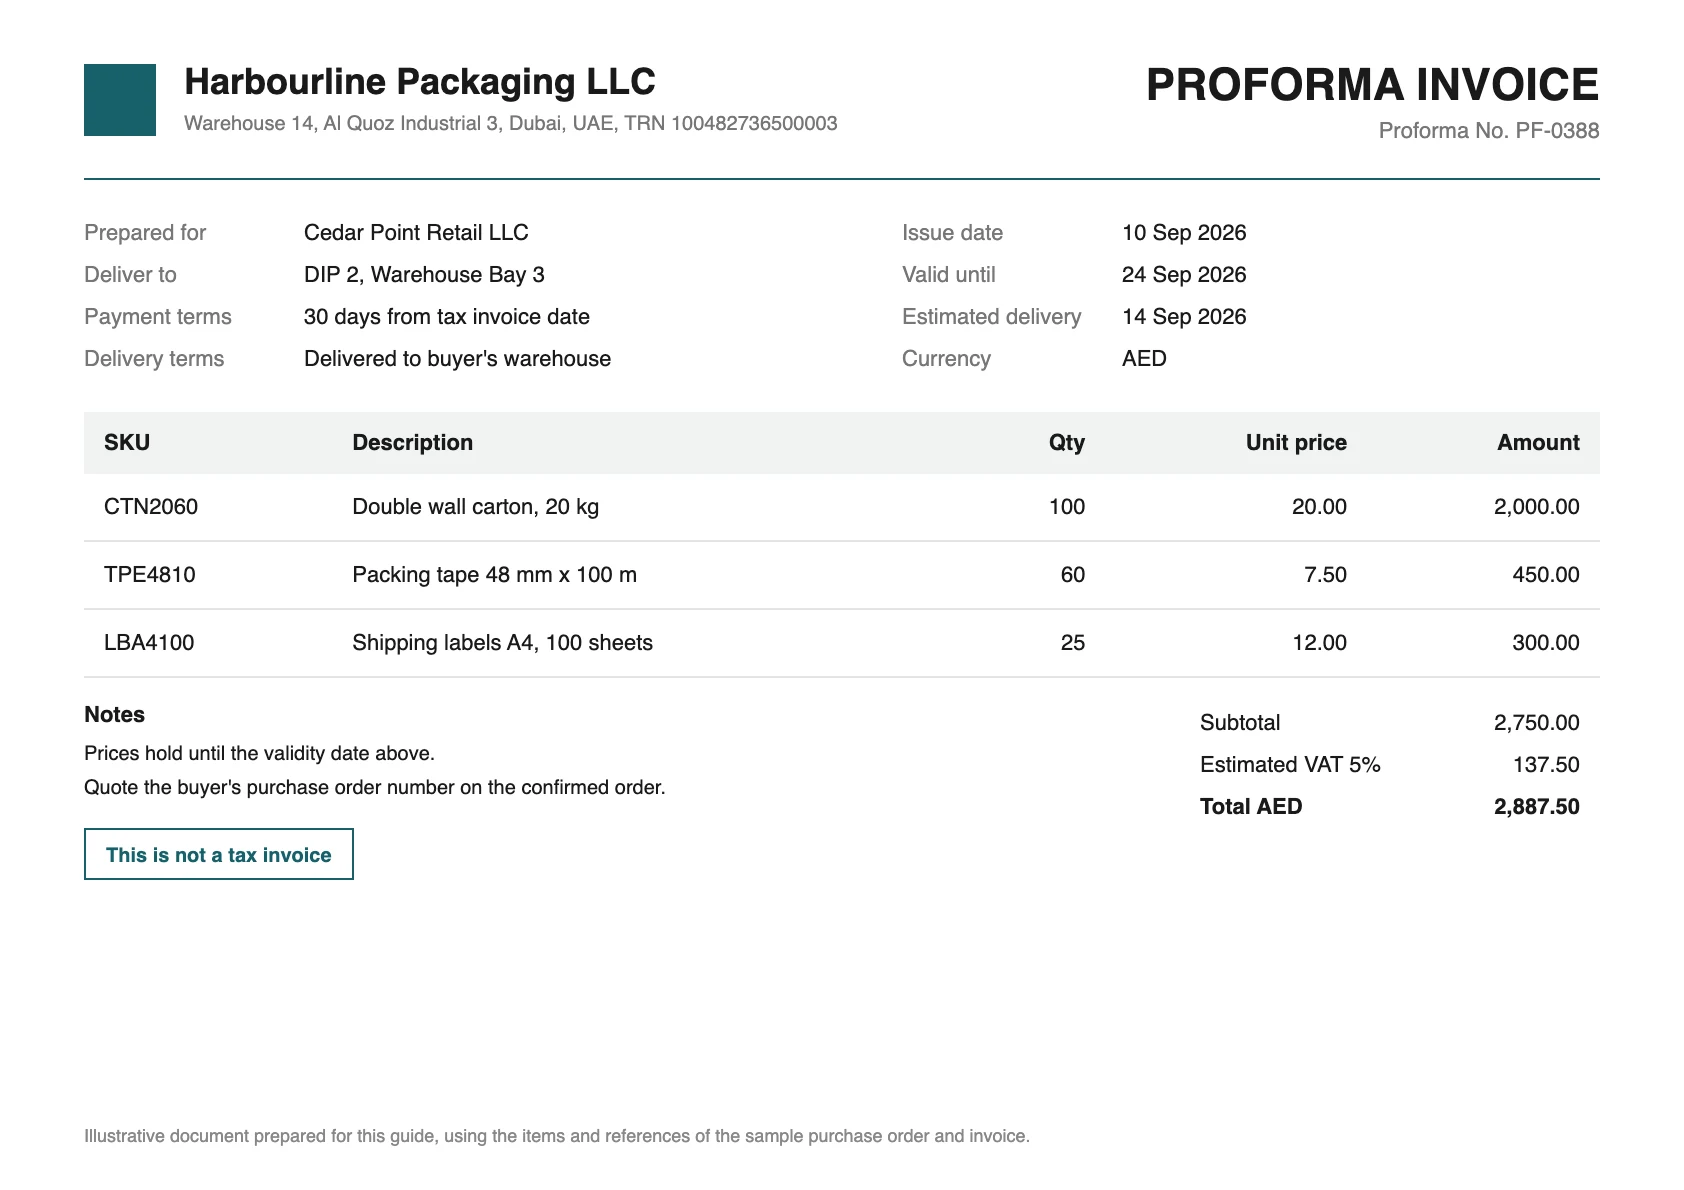
The sample above was prepared by Harbourline Packaging LLC for Cedar Point Retail LLC on 10 September 2026. Its number is PF-0388 and it is valid until 24 September. It quotes three items for AED 2,750 before VAT, AED 2,887.50 with the estimated VAT, on payment terms of 30 days from the tax invoice date.
The later documents can be read against it:
| Document | Issued by | Date | Reference | Total |
|---|---|---|---|---|
| Proforma invoice | Supplier | 10 Sep 2026 | PF-0388 | AED 2,887.50 |
| Purchase order | Buyer | 12 Sep 2026 | 2026-117 | AED 2,887.50 |
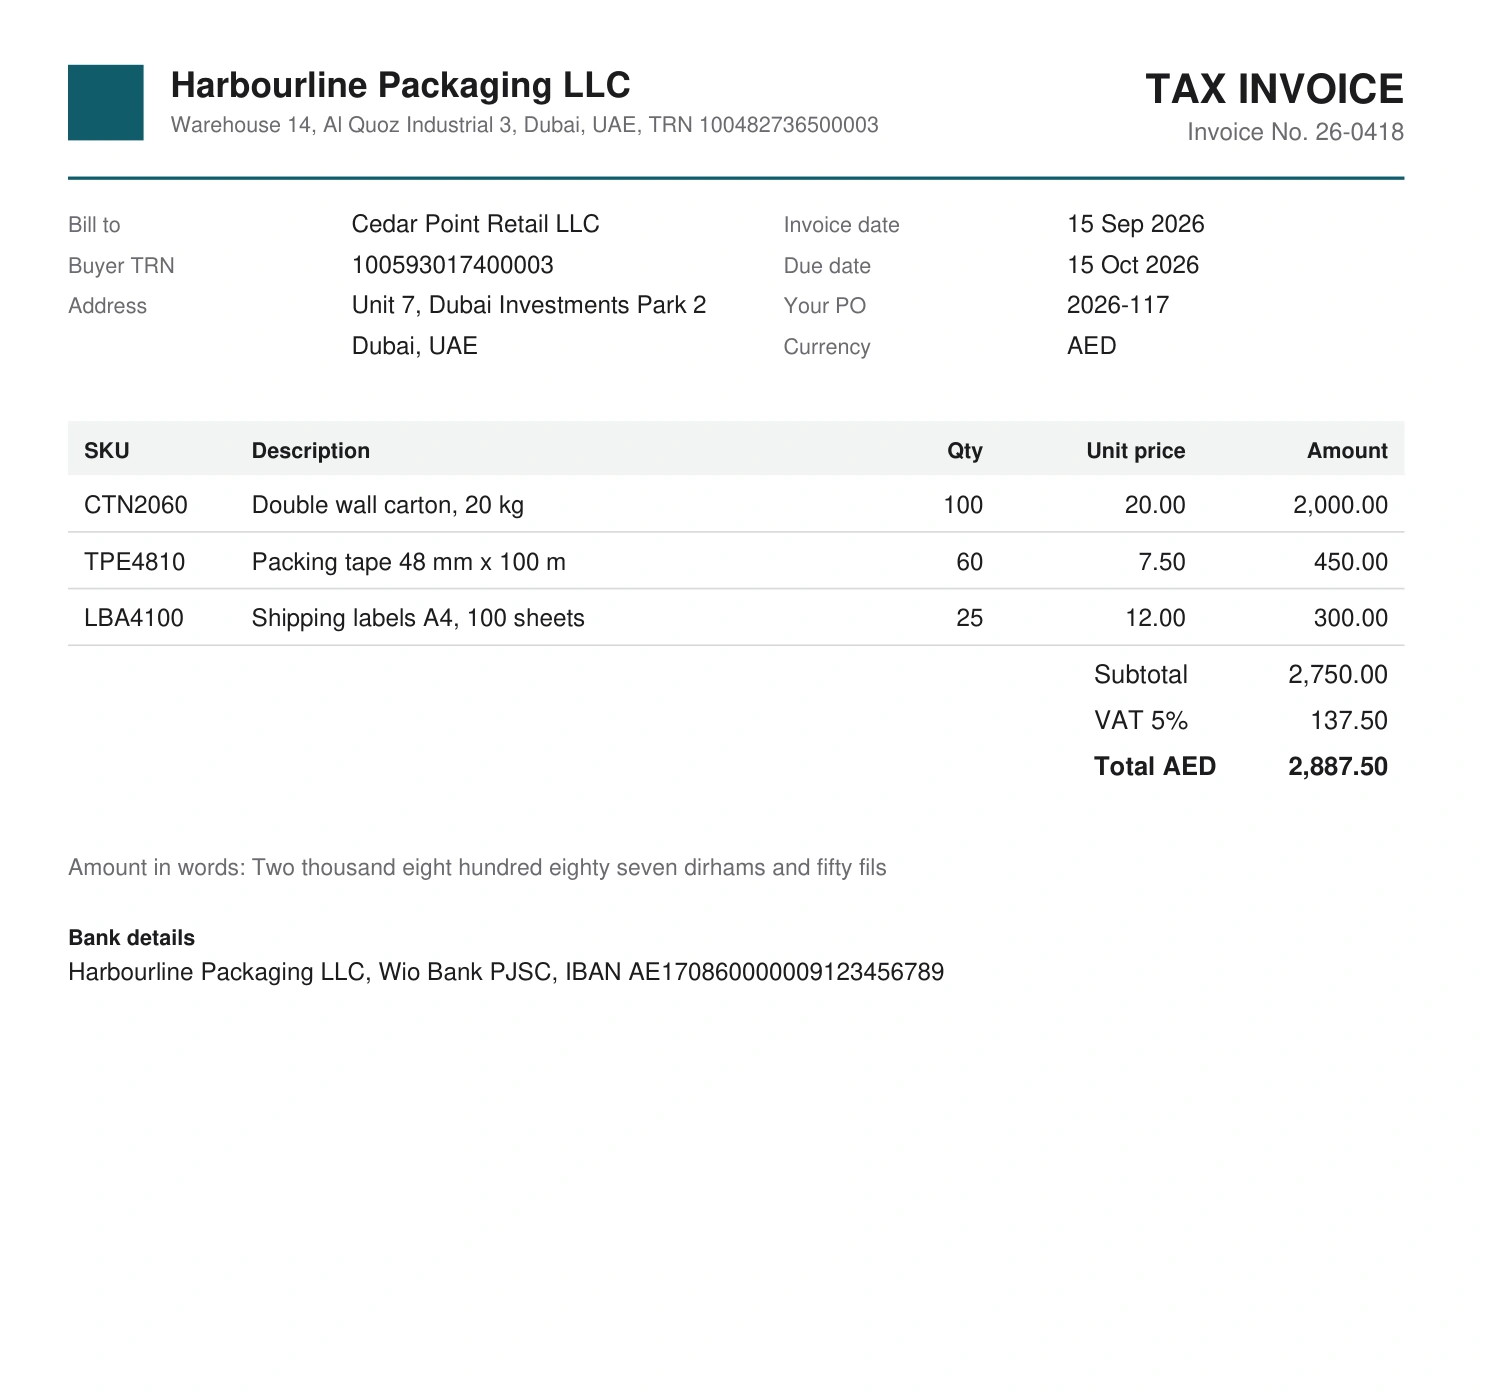
| Tax invoice | Supplier | 15 Sep 2026 | 26-0418 | AED 2,887.50 |
The order was raised inside the validity period, for the same items and prices. The tax invoice quotes the order number and falls due on 15 October, which is 30 days after its date. Each of those points is a separate check, and each can fail on its own.
For the fields of the order itself, see the purchase order guide. In the UAE the buyer's order is often called an LPO; that guide explains the term.
Proforma invoice vs tax invoice
A proforma states what the supplier intends to bill. A tax invoice bills a supply that is being made. The difference shows up in five places:
| Question | Proforma invoice | Tax invoice |
|---|---|---|
| When is it issued? | Before the supply or before the order is confirmed | When the supply is made, within the period the tax rules set |
| What is it for? | Agreeing terms, approval, advance payment | Billing the supply |
| Is it entered in the accounts? | Not as a payable or a sale | Yes |
| Does it support VAT recovery? | No | Yes, when it meets the legal requirements |
| Can it change? | Yes, the supplier can reissue it until terms are agreed | A correction goes through a credit note or a corrected invoice |
In the UK, HMRC states that entitlement to input tax depends on a valid VAT invoice and that "pro-forma or similar invoices are not, therefore, acceptable evidence". Where the issuer of a pro-forma later receives payment or makes the supply, "a full VAT invoice must be issued within 30 days". HMRC VATREC9020.
In the UAE, Article 59 of the VAT Executive Regulation lists the particulars of a tax invoice, and the first is the words "Tax Invoice" clearly displayed. A document headed "Proforma invoice" does not carry them. The text is published with the Federal Tax Authority's VAT legislation.
Tax rules differ by country and change over time. Treat these two examples as the reason to check the heading, and confirm the current requirement for your own jurisdiction.
Proforma invoice vs quotation, purchase order and commercial invoice
These documents share most of their fields, which is why they get confused. They differ in who issues them and what they establish.
| Document | Issued by | What it establishes |
|---|---|---|
| Quotation | Supplier | The price and terms on offer |
| Proforma invoice | Supplier | What the bill will look like if the buyer proceeds |
| Purchase order | Buyer | What the buyer has ordered and at what agreed price |
| Commercial invoice | Supplier | The goods actually shipped and their value, in cross-border trade |
| Tax invoice | Supplier | The supply billed and the tax charged on it |
The International Trade Administration notes that pro forma invoices contain much of the same information as the formal quotation and "in many cases can be used in place of one". A proforma does not replace the buyer's order, and it does not replace the final invoice.
Paying against a proforma: an advance payment example
The following is an illustrative variation on the sample, with different payment terms.
Suppose Harbourline asked for 50% in advance. The proforma total is AED 2,887.50, so the advance is AED 1,443.75. Cedar Point pays it against PF-0388. After delivery, the supplier issues a tax invoice for the full supply.
| Step | Amount |
|---|---|
| Proforma total | AED 2,887.50 |
| Advance paid against the proforma | AED 1,443.75 |
| Tax invoice total for the supply | AED 2,887.50 |
| Balance still to pay | AED 1,443.75 |
Three errors are possible here, and none of them needs a forged document:
- The final invoice is paid in full on top of the advance, an overpayment of AED 1,443.75.
- Both the proforma and the tax invoice are entered as bills, so the same purchase is counted twice.
- The supplier never sends a tax invoice, and the buyer holds only the proforma.
HMRC lists the same pattern among the risks of pro-forma invoices: a customer using the pro-forma to support input tax deduction, claiming input tax twice against both documents, or a supplier relying only on the pro-forma. HMRC VATREC9030.
Checks before the final invoice is paid
Supplier and bank details
Confirm that the final invoice comes from the supplier named on the proforma. If the bank details differ from the earlier document, confirm the change through a contact you already hold. For signs that a file itself was edited, use Fraud Detection.
Validity and version
Check that the order was placed before the validity date, and that the invoice follows the version of the proforma the buyer approved. A reissued proforma with a new price should not be compared with an order raised on the old one.
Lines, prices and arithmetic
Compare each line: item, quantity, unit price and line total. Then check that the lines add up to the subtotal and that the tax is calculated on it. In the sample, 2,000 + 450 + 300 = 2,750, and 5% of 2,750 is 137.50.
The advance, counted once
Where an advance was paid, the balance paid on the final invoice should be the invoice total less that advance. Keep the proforma, the payment record and the tax invoice together.
Quantity received
A proforma and an invoice can agree while the delivery is short. That comparison needs the receiving record; see three-way matching and the goods received note guide.
Comparing the documents with Document Automation
Document Automation reads the uploaded files, extracts the requested fields and line tables, and compares documents with each other using configured checks. Each extracted value keeps the place on the page where it was read.
An invoice-and-PO template is already available. A proforma check uses the proforma as the reference document: the fields, the line keys and any tolerance are agreed with the customer and tested on its files before use. The result lists the compared values and the specific differences, and it can be returned as JSON.
Discuss a proforma and invoice check with Document Automation.
Proforma invoices for UAE and GCC teams
Check the heading first. A file headed "Proforma invoice" and a file headed "Tax Invoice" from the same supplier can show identical lines and totals, and only one of them is the tax document.
Test with real supplier files, including mixed English and Arabic layouts and the supplier's own item codes. The same checks apply whether the review sits with an in-house finance team or an outside accounting firm. A document comparison shows where two files agree or differ. It does not establish that an invoice meets VAT or electronic invoicing requirements.
Frequently asked questions
Is a proforma invoice a tax invoice?
No. A proforma is issued before the supply and states the intended terms. The tax invoice is issued for the supply itself and is the document that supports VAT recovery where it meets the legal requirements.
Can a buyer pay against a proforma invoice?
Yes, where the parties have agreed an advance payment. Keep the proforma and the payment record, and expect a tax invoice for the supply. Pay only the remaining balance when it arrives.
Is a proforma invoice legally binding?
That depends on the agreement between the parties and the law that governs it. On its own, a proforma sets out offered terms. Treat enforceability as a legal question for the specific contract.
What is the difference between a proforma invoice and a commercial invoice?
A proforma describes a shipment that has not yet been made. A commercial invoice describes the goods actually shipped. The International Trade Administration notes that a pro forma may not be a required shipping document.
Does a proforma invoice need a number?
The sources cited here set no numbering rule for proformas. A reference and an issue date are still worth having, because the order and the final invoice can then point to one version.
Sources
- HMRC VAT Trader Records manual: pro-forma invoices, introduction (VATREC9010)
- HMRC VAT Trader Records manual: can a pro-forma invoice be used to account for VAT? (VATREC9020)
- HMRC VAT Trader Records manual: risks associated with pro-forma invoices (VATREC9030)
- International Trade Administration: pro forma invoice
- UAE Federal Tax Authority: VAT legislation